


The first price estimate for my 40th birthday party came back, and I almost killed the whole event.
I’ve never thrown myself a party. I don’t like people singing happy birthday to me. And I’m a financial planner, so I know what that money could turn into if I left it alone to compound. Saying no felt like the responsible call.
That’s what most of us have been taught. The big risk with money is enjoying it too much or too soon. So we say no. Or we say “next year,” and we call it discipline.
The problem is that next year has a way of turning into ten.
My wife, Jessica, encouraged me to have the party anyway. I’m glad she did, because that night made me wonder if we’ve been worried about the wrong risk all along.
The night I almost cancelled
We threw an open house at our place starting at 4pm.
We spent more than I normally would: catered from my favorite restaurant in town, a full bar with bartenders, and a big tent that extended our garage. But the point was never the doing it big. The point was to spend good money on the people I love.
The credit goes to my wife. She encouraged me to do it when I was ready to call it off, and then she coordinated the entire thing. She killed it.
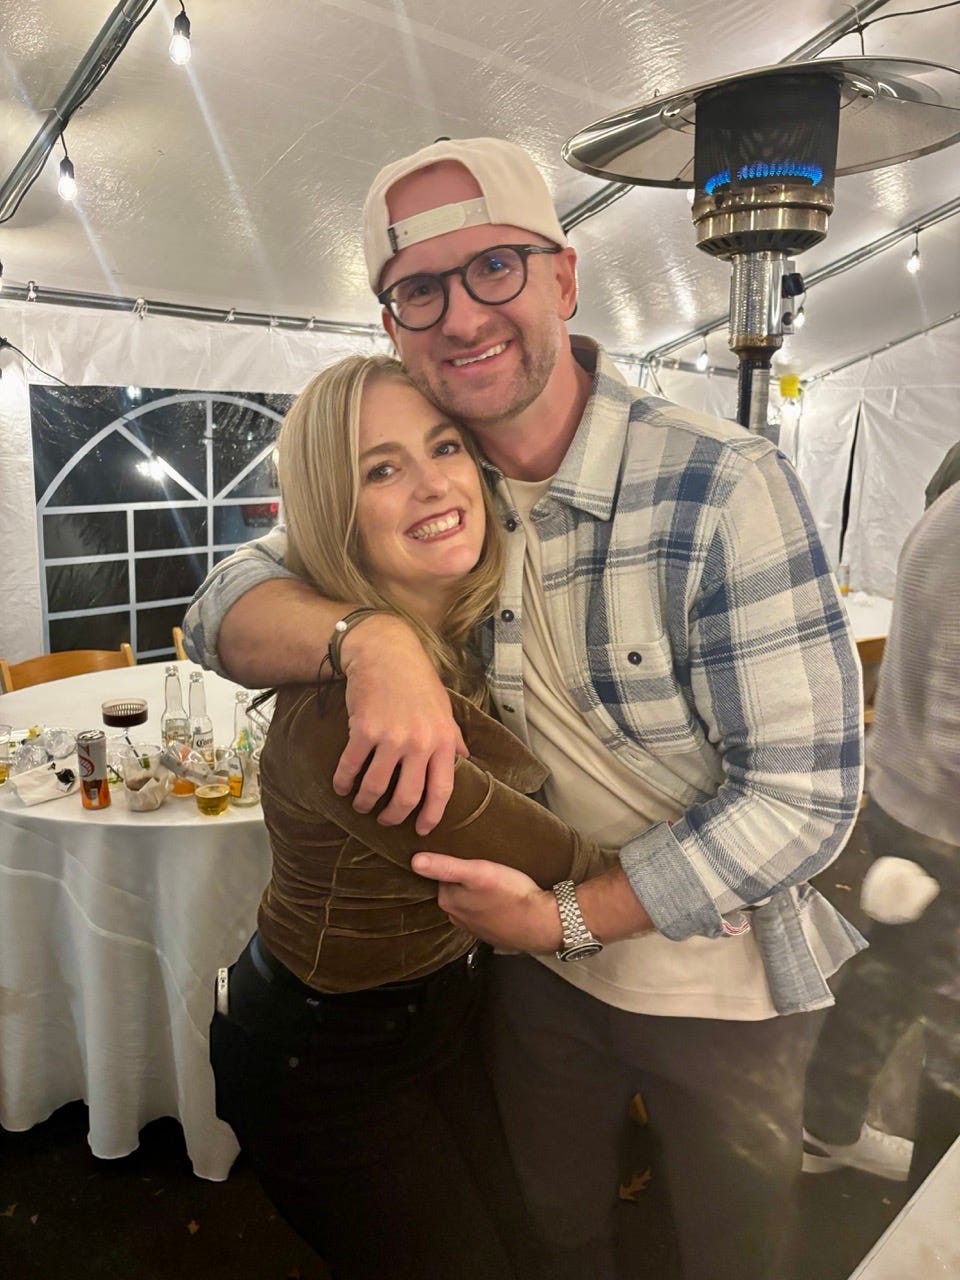
About 70 people came: my college football friends, friends from high school, new friends from the community, kids sport parents, and our neighbors.
The party ran until we ran out of food and beer, which ended up being around 1am.
What stuck with me most wasn’t the food or the awesome bartenders. It was getting people I love from different eras of my life together in one place.
The party was great. But the real story is why I almost didn’t have it.
We postpone things and call it discipline
If you’re a high earner in your 30s or 40s, you’re probably very good at waiting.
You wait on the next vest, the next promotion, the year things finally calm down at work. You say “next year” to the trip, the reunion, and the weekend with old friends.
It feels like discipline.
But the windows that matter most never slam shut. They narrow slowly, so there’s never an obvious deadline. There’s always one more vest, one more year, and one more good reason to wait.
Meanwhile, the scoreboard most of us use tracks one thing: net worth. It goes up, and there’s no line on the statement for how long it’s been since you saw your best friends.
For me, it had been about 10 years.
My college roommate was the best man in our wedding, and our wedding was the last time we’d been together. Nothing happened between us. It was distance, raising families, building careers, and busy schedules.
The decade just got away from us.
We still talked regularly. We just hadn’t gotten together. I used to think that counted as staying close. But talking isn’t the same as being together, and it took him flying in from the west coast of Canada for my 40th for me to really feel the difference.
That’s what postponing actually costs.
So why change now? For me, it clicked when I thought about the stages of life.
Three stages of life, and the good one is now
In my 20s, I had all the time in the world and great health. I was also broke.
Now the parents I grew up around, my own included, are in their 60s and 70s. They have time because they’re retired, and money from years of working and saving. But like most people that age, they’re slowing down. They don’t have the health and fitness they used to.
And then there’s me, at 40. I have my health, I have time on my side, and I’m fortunate to be in a good financial position. That’s a rare window, and I don’t want to take it for granted.
For most of life, you get two out of three. In your 20s you have time and health but no money. In your 60s and 70s you have time and money but less health. Your 30s and 40s are the one window where you can have enough of all three at once. Not each one at full strength. But enough.
That’s the idea I keep coming back to:
Money is worth more when it arrives while your health, time, and people can still use it.
A dollar at 40 and a dollar at 72 are the same balance. They buy very different amounts of life.
A 72nd birthday party with the people you love would still be a great night. But the version where an old friend flies across a continent, the party runs until the food and beer are gone, and you’re still up at 1am laughing around the fireplace? That version has an expiration date.
I wrote a while back that you can always make more money, but time with an 8-year-old runs out in about ten summers. I think the same math applies to old friends and aging parents. The money can wait a year. The window for some of these nights can’t.
But I’m a planner, and I’d be lying if I said the other side doesn’t have a strong case.
The honest case for waiting
It’s a good case, and a lot of it comes from authors I respect.
Time is the biggest lever in compounding. Every dollar I spent on that party is a dollar that won’t get decades to grow.
The money you don’t spend is what builds wealth. It’s also what buys options: changing careers, taking time off, or getting through a bad year without panic.
None of us knows how long we’ll live. If I spend too freely now, I could be betting my future on what I want today.
And what I want will change. What I care about at 40 won’t be exactly what I care about at 55. Any extreme plan, spend it all or save it all, assumes I’ll stay the same person. I won’t.
I believe all of that. It’s most of my job.
Here’s how I square it. It comes back to the window of opportunity.
Your portfolio’s window stays open for decades. Patience is the right rule there, and time is on its side. But the window for certain nights with certain people is closing slowly, whether you’re watching or not.
My wife Jessica said it to me the night after the party: regardless of what’s happening, life keeps moving on.
Compounding rewards waiting. My health, my parents’ health, my friendships, and my kids’ summers don’t. None of them waits for my net worth to hit a certain number.
The mistake is treating every window like your portfolio’s, as if it will stay open as long as you need it to.
So what made the party OK for me? Before I said yes, I checked. I’m hitting my savings targets for the year, and I’m on track with all my business goals. The plan didn’t need this money. It was extra, and I got to spend it on purpose guilt free.
That’s when I knew this was the right time to treat the people I love to a night on me.
I’ve learned to be patient with my investments, but not with my life.
So how do you actually do that without putting your financial future at risk?
How to spend on your people without betting the plan away
I don’t know your numbers, and I won’t pretend to. This is just how I think about it. It’s the filter I run my own decisions through, and the one I used for this party.
Fund the floor first. Before a big spend on your people or an experience, make sure the essentials are covered: savings targets on track, a cushion in place, and a plan that doesn’t depend on this money.
Define enough. If you’ve never put a number and a purpose on “enough,” every purchase that’s more than you wanted will feel like a loss. The goalposts keep moving, and wealth becomes the score instead of the tool.
Name who you’re postponing. Write down the people you keep saying “next year” to: the roommate, the old team, the friends from home. If the list is long, that’s your signal.
Spend on purpose, not to extremes. One party, one trip, or one reunion isn’t a lifestyle overhaul. And since you’ll change, I’d avoid extreme recurring commitments in either direction.
Have a partner to complement you. I almost killed this when the first estimate came in. Jessica is the reason it happened, and she’s the reason it was as good as it was. If you’re the one who always says no, it helps to have someone in your life who can see what the money is for.
Keep your portfolio’s window open. None of this means stop saving or stop investing. It means don’t use your net worth growing as a reason to postpone your life.
The next morning
I woke up exhausted.
Staying up until 1 in the morning hanging with my friends and laughing around the fireplace doesn’t happen much anymore.
Then the texts started coming in. People told me how great it was to get out and hang out like we used to. Seventy of the people I love, from different eras of my life, in one place for one night.
It was a special night, and money well spent.
We’re told the risk is enjoying your money too soon. I think the bigger risk is having the money and no longer having the health, time, or people to spend it with.
One of those risks is reversible. The other one isn’t.
So be patient with your investments, but not with your life.
— Ryan


Whenever you’re ready, there are 2 other ways we can help you:
Join The Opulus Method Newsletter — Every Tuesday, I share strategies that help high-income millennials build wealth without sacrificing their life. Join 4,000+ readers.
Work With Us 1-on-1 — We’ll build your personalized strategy to cut your taxes, maximize your income, and grow your wealth month after month. You focus on living your life. We handle the financial strategy and execution.
Opulus, LLC (“Opulus”) is a registered investment advisor in Pennsylvania and other jurisdictions where exempted. Registration as an investment advisor does not imply any specific level of skill or training.
The content of this newsletter is for informational purposes only and does not constitute financial, tax, legal, or accounting advice. It is not an offer or solicitation to buy or sell any securities or investments, nor does it endorse any specific company, security, or investment strategy. Readers should not rely on this content as the sole basis for any investment or financial decisions.
Past performance is not indicative of future results. Investing involves risks, including the potential loss of principal. There is no guarantee that any investment strategies discussed will result in profits or avoid losses.
All information is provided “as-is” without any warranties, express or implied. Opulus does not warrant the accuracy, completeness, or reliability of the information presented. Opinions expressed are those of the authors, Ryan Greiser and Francis Walsh, and are subject to change without notice.
Opulus is not responsible for any errors or omissions, nor for any direct, indirect, or consequential damages resulting from the use or reliance on this information. Use of the content is at your own risk. This content is not intended as an offer or solicitation in any jurisdiction where such an offer or solicitation would be illegal.
Wise advice. The same can be said about passing along money to the next generation— sometimes the right time to help your kids is not after you die and leave them a compounded fortune (it may be now, when they’re struggling with a mortgage or medical bills). “Hey Dad, thanks for the inheritance, but now that I’m nearing retirement and the kids are gone … I don’t really need it - where were you 20 years ago?”